

myFICO - Credit Score Tracking

- 4.47K Reviews
- 4.3
- Downloads
- 1,000,000+
Our take on myFICO - Credit Score Tracking from Appgk
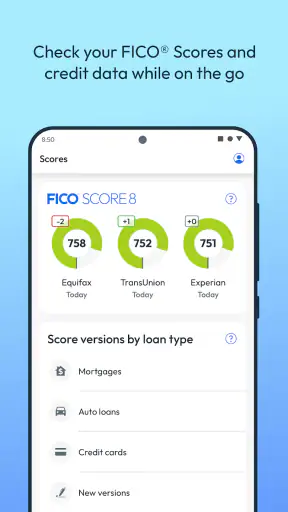
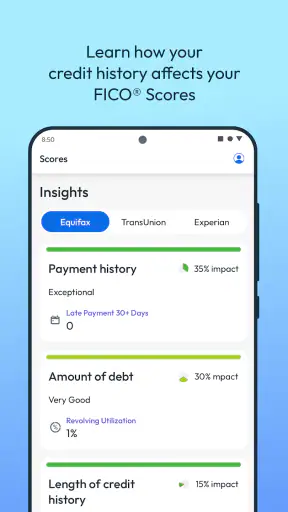
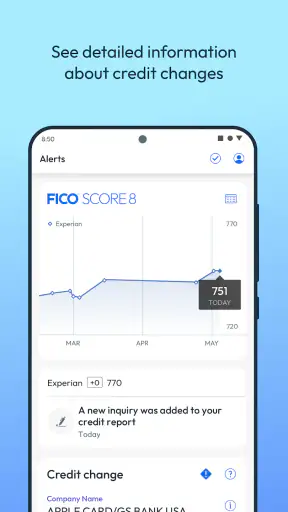
Managing credit can feel abstract until a lender makes a decision that affects your home, car, or next card. I found myFICO most useful as a focused finance app for people who want to understand that part of their financial profile without constantly searching through separate websites. It comes from FICO, is free to install, and is rated for Everyone, which makes it approachable for a broad audience. Its purpose is straightforward: help you view your FICO Score and an Equifax credit report in one place.
That simple purpose is also the key to judging it fairly. This is not a complete budgeting system, a bill-payment tool, or a replacement for checking every account directly. I see it as a credit-monitoring companion. When I used it with that expectation, the app felt more focused and easier to evaluate. When I expected a full personal-finance dashboard, its narrower scope became more noticeable.
How clearly myFICO supports different ways of using a credit app
Readability and navigation are strongest when the goal is specific
The app’s clearest advantage is that its subject is easy to understand: credit information. A person opening it to check a score, inspect a report, or prepare for a loan conversation is unlikely to wonder what the central purpose is. That focus matters because financial applications can become confusing when they mix spending charts, investments, offers, alerts, and educational material on the same screen.
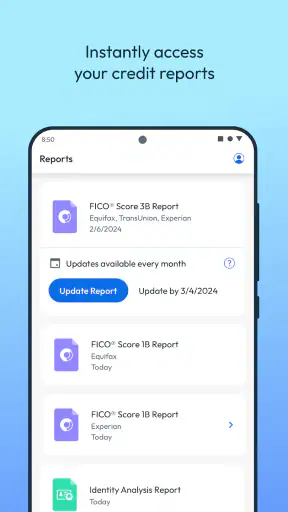
I would approach it with one question at a time. For example, if I were preparing to apply for a mortgage, I would first review the score, then read through the Equifax report rather than trying to interpret everything in a single glance. This workflow reduces the temptation to treat a single number as the whole story. A score is useful, but the report gives the context needed to spot unfamiliar accounts, outdated information, or details worth discussing with a lender.
Best Parts of myFICO - Credit Score Tracking
Things to Keep in Mind About myFICO - Credit Score Tracking
The information is also easier to process when I slow down and compare related details instead of simply looking for a “good” or “bad” result. Someone who is new to credit may benefit from reading the surrounding explanations carefully. A more experienced user can use the app as a quick checkpoint before making a major financial decision.
There is a practical readability lesson here: credit information should not be consumed while distracted. I would avoid checking it in a crowded commute or while rushing through a loan application. Even a well-organized financial interface can feel dense when it contains unfamiliar terms. The best experience comes from opening it with enough time to read the report and note questions.
News and Features Related to myFICO - Credit Score Tracking

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
The app has a current version of 4.0.23.4 and requires at least iOS or Android version 12. That requirement is important for inclusion. People using older phones or operating systems may not be able to use it, even if the app’s subject matter would otherwise suit them. For users with a compatible device, the relatively focused design should be less intimidating than a finance app that tries to cover every area of money management.
Credit reports need a slower reading style than ordinary app content
A credit report is not casual reading. It can include names, account information, payment history, and other personal details that deserve attention. I would not recommend skimming it in the same way I might skim a news feed. Instead, I would check one section at a time and keep a note of anything that needs follow-up outside the app.
Don't want to read the full review?
This is especially helpful for people who find large blocks of financial information tiring. Breaking the task into small sessions can make the experience more manageable: review the score first, examine account entries later, and return to questions when there is enough concentration to deal with them. The app is more useful as a recurring reference than as something to open only during a financial emergency.
For users with reading difficulties, unfamiliar credit vocabulary may still be a hurdle. The app’s focused subject does not automatically make every term simple. I would pair it with plain-language financial guidance when a report entry is unclear, rather than guessing what a technical phrase means. That is a sensible habit with any credit-report service.
Screenshots
Motor and sensory considerations during routine checks
Credit monitoring does not usually require rapid actions, which is a quiet strength for people who need more time or prefer deliberate interaction. I can imagine a user checking the app with a stylus, using larger system text, or taking breaks between sections without losing the basic purpose of the session. Since the task is mainly reviewing information, accuracy and patience matter more than speed.
That said, I would not assume that every visual or motor need is automatically handled. A person with low vision may need to adjust the device’s display settings and test whether report text remains comfortable to read. Someone with limited dexterity may find account navigation or authentication steps more demanding than simply viewing a score. These are not reasons to dismiss the app, but they are good reasons to test it before relying on it for an urgent application.
For users with hearing-related needs, the core activity is primarily visual, which can make the app more practical than a service that depends heavily on spoken instructions. However, financial services can still involve alerts, messages, or outside communication. I would keep important follow-up details in a written note and avoid treating an in-app check as the only record of a problem.
People sensitive to visual clutter may appreciate the app’s narrow purpose, but credit information itself can be stressful. A score that changes, a report entry that looks unfamiliar, or a warning that needs investigation can create a strong emotional reaction. I recommend checking it at a calm time and deciding in advance what action to take if something looks wrong. That turns the app from a source of anxiety into a structured review tool.
Situational access: when the app fits real financial decisions
One realistic use case is preparing for a mortgage discussion. Before speaking with a lender, I would open the app, review my FICO Score, and read the Equifax report for obvious inconsistencies. I would then write down questions instead of relying on memory. This does not guarantee a lending outcome, because lenders consider their own criteria, but it gives me a more informed starting point than applying without reviewing my credit information.
A similar workflow makes sense before applying for a credit card or loan. The important trade-off is timing. Checking information shortly before an application may reveal something worth investigating, but discovery does not mean an issue can be corrected immediately. The app is therefore most valuable when used as part of ongoing preparation, not as a last-minute repair service.
It can also help someone who is rebuilding credit stay connected to progress without opening a broader money-management platform. A user may prefer to track spending elsewhere and use this app only for the credit side of the picture. That separation can be useful for people who become overwhelmed when one application combines transactions, budgets, investments, and credit details.
For a caregiver or family member helping someone understand credit, the app may provide a concrete starting point for discussion. I would still protect the account holder’s privacy and avoid sharing sensitive report details casually. The most inclusive approach is collaborative: let the person whose credit is being reviewed control the session, while the helper explains terms or writes down questions.
Travel and weak connectivity are situations where I would be more cautious. I would not wait until an airport, hotel lobby, or rural area to discover that I need access to credit information. Before an important application, I would check the app at home and save only the non-sensitive notes needed for the next conversation. I would not copy personal report details into an insecure note or message simply for convenience.
Where it compares well with broader finance alternatives
Compared with a general budgeting app, myFICO has a sharper purpose. A budgeting tool may be better for tracking spending, setting categories, or seeing where money goes each month. This app is the better fit when the question is specifically about a FICO Score or an Equifax report. I would not replace a budget with it, and I would not choose a budgeting app when my immediate concern is reviewing credit information.
Compared with checking a credit report through a browser, the app offers a more direct mobile routine for people who prefer using a phone. That convenience can encourage regular reviews. The trade-off is that a browser may feel easier for users who need a larger screen, want to compare several documents side by side, or depend on desktop assistive tools. In that situation, the mobile format may not be the most comfortable option.
Compared with a lender’s own portal, the app is more useful for personal preparation because it is not tied to one application conversation. A lender can explain its process and requirements, while myFICO helps me look at my credit information before I enter that process. Neither should be treated as a complete substitute for the other.
The developer, FICO, is also central to the app’s identity because the product is built around the FICO Score rather than a generic financial wellness number. That distinction matters to users who specifically want to follow the scoring model lenders commonly discuss. It also means people should avoid assuming that every score shown by every financial service will match exactly; different services can present different models or information sources.
Remaining barriers that affect trust and independence
The first barrier is interpretation. A person can open the app easily and still misunderstand what a score means, why it changed, or how a report entry should be challenged. I would treat the app as an information source, not an automatic financial adviser. If a decision involves a home, a large loan, or suspected identity theft, I would use the report as evidence for further action and seek appropriate guidance rather than relying on a quick in-app conclusion.
The second barrier is emotional accessibility. Credit scores can make people feel judged, particularly after missed payments or financial hardship. An app that presents a number cannot remove that pressure. My practical advice is to focus on observable details and next steps: identify an unfamiliar entry, record the date, gather supporting documents, and contact the relevant organization through a trusted channel. That approach is more useful than repeatedly refreshing the score.
Privacy is another reason to be deliberate. Credit information is sensitive, so I would use a device protected by a passcode and avoid opening the app on a shared phone. I would also be careful when helping another person. Accessibility should include independence and dignity, not just the ability to display information on screen.
The operating-system requirement can exclude users with older hardware, and the mobile format may not suit people who need extensive desktop magnification or keyboard-based navigation. Someone in either group may be better served by a browser-based credit service or by asking a trusted support person to help access the information through a larger device. That is not a criticism of the app’s purpose; it is a reminder that the most suitable tool depends on how a person works.
There is also a conceptual barrier for users who expect a complete picture of financial health. A credit report does not show every part of someone’s finances, and a score is not a personal measure of responsibility or stability. I would pair this app with a budget, account statements, and direct communication with lenders when appropriate. Its value increases when it occupies the right place in that larger routine.
Who will get the most from this focused credit companion
I think the app is a strong match for someone who wants a dedicated way to check a FICO Score and review an Equifax report without adopting a full financial dashboard. It is also useful for people preparing for credit cards, mortgages, or loans who want to inspect their information before speaking with a lender. The free price lowers the barrier to trying it, while its Everyone rating makes it suitable for a wide range of users.
Its popularity suggests that many people find this focused approach worthwhile: the app has an average rating of 4.3 from around twelve thousand ratings, with more than one million installs. I would read those figures as evidence of broad interest rather than a promise that every user will find the interface effortless. Credit circumstances, device needs, and expectations vary considerably.
I would skip it if my main goal were envelope budgeting, investment management, bill scheduling, or detailed spending analysis. I would also look for another route if I needed a large-screen workflow, had an incompatible operating system, or wanted a service centered on a different credit-report source. The right choice depends less on the app’s general reputation than on whether its specific credit focus matches the question I need answered.
My inclusive verdict after using it as a credit-review tool
myFICO is most successful when I use it as a calm, focused checkpoint before an important financial conversation. It brings the FICO Score and Equifax report into one mobile experience, and that can make credit review feel more approachable than searching across unrelated services. The narrow scope is a benefit for users who want clarity, but a limitation for anyone expecting a complete money-management suite.
From an inclusion perspective, its strongest quality is the ability to support slower, deliberate review rather than demanding constant interaction. Its remaining challenges are just as important: financial terminology can be difficult, sensitive information requires careful handling, and the mobile format or operating-system requirement may not suit everyone. I would test the reading experience on the intended device and plan how to record follow-up questions before depending on it for a major application.
My recommendation is measured but positive. If you want a free finance app dedicated to checking your FICO Score and Equifax credit report, it is worth trying. Use it regularly enough to understand your own credit history, read reports rather than chasing a number, and treat unusual information as a reason to investigate. The best way to use myFICO is as one accessible piece of a broader financial routine, not as the entire routine.
myFICO - Credit Score Tracking FAQ
What is myFICO - Credit Score Tracking used for?
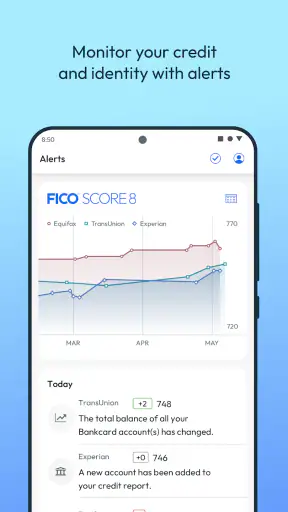
myFICO is designed to help users monitor their FICO® credit scores, review credit-report information, and understand the factors that may influence their credit profile. After signing in, you can view available score updates, track changes over time, and access explanations intended to make credit information easier to follow. The exact features depend on your subscription and the plan available in your region.
Is myFICO free to download and use?
The app may be free to download, but many of its most useful features require a paid myFICO subscription or an eligible account. Depending on the plan, access can include score updates from different credit bureaus, multiple FICO® Score versions, credit reports, monitoring alerts, and identity-related tools. Before subscribing, review the current pricing, billing frequency, trial terms, and cancellation policy shown in the app.
Which credit scores and credit bureaus does myFICO provide?
myFICO focuses on FICO® Scores rather than relying only on educational scores from other scoring models. Available scores, reports, update frequency, and bureau coverage vary according to the subscription selected. Some plans may provide information from one bureau, while others offer broader coverage and additional score versions. Users should check the plan details because availability can also depend on account and regional limitations.
Can myFICO improve my credit score or correct errors on my credit report?
myFICO can help you understand your credit information, identify factors affecting your score, and monitor for changes, but it cannot directly raise your score or guarantee approval for credit products. If you find inaccurate information, you generally need to dispute it with the relevant credit bureau or the company that supplied the data. The app may offer guidance, but users remain responsible for taking corrective action.
Is my financial information safe when using myFICO?
Because myFICO handles sensitive credit and identity information, users should review its privacy policy, security practices, and account requirements before signing up. Use the official app listing or myFICO website, create a strong unique password, and enable available security protections. Avoid entering account details through unofficial links. No service can eliminate every risk, so regularly reviewing account activity and monitoring alerts is still important.











